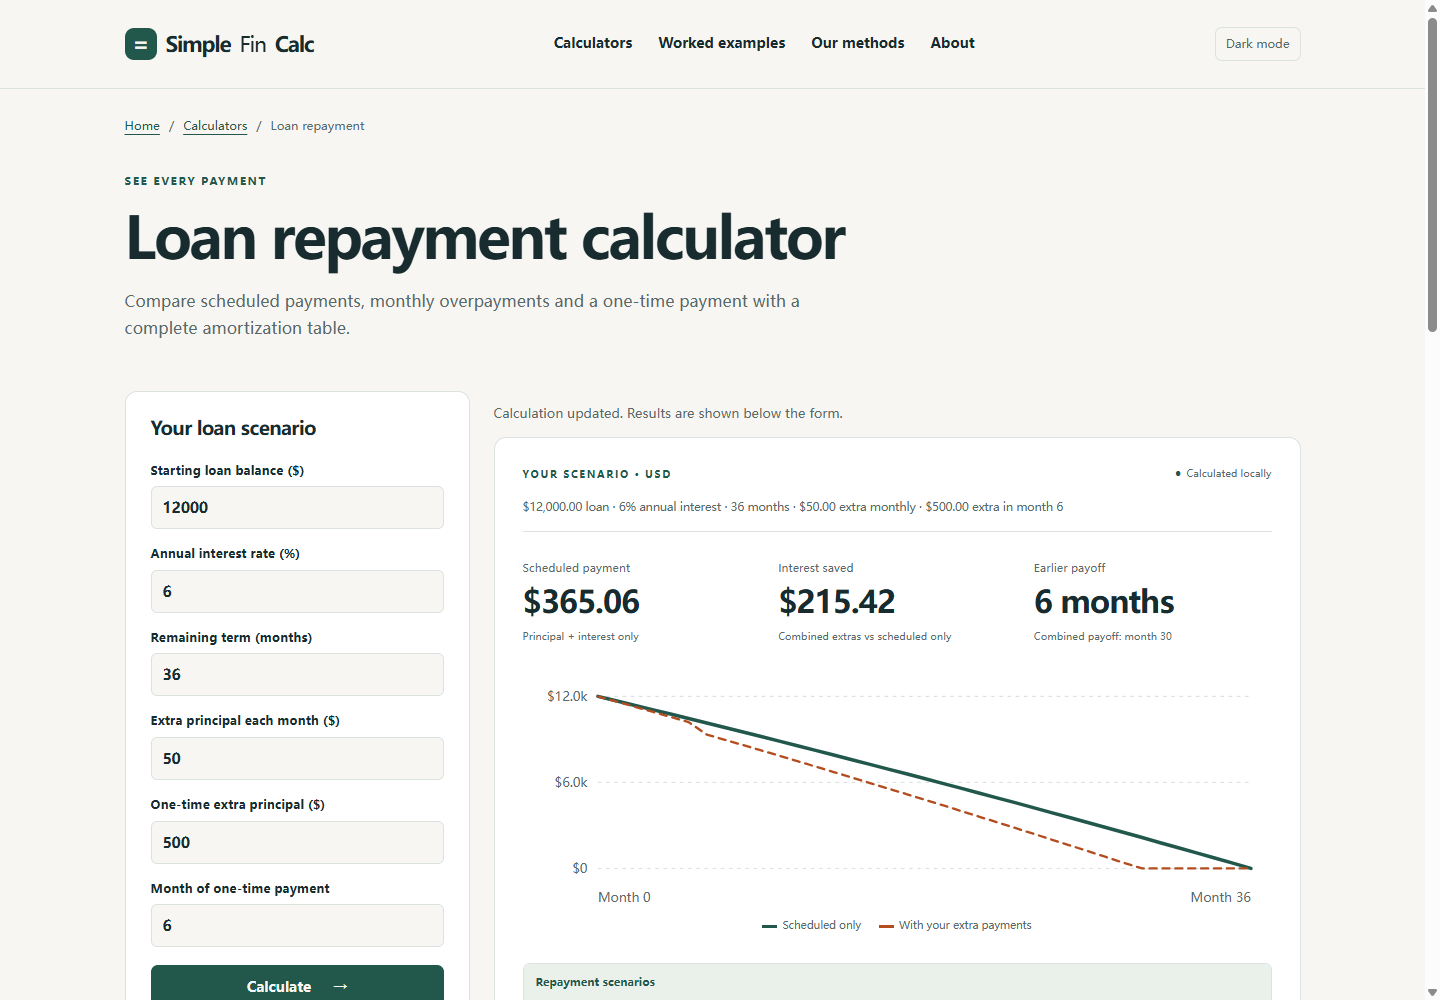
Start with a $12,000 loan balance, a fixed 6% annual interest rate and 36 months remaining. The model charges monthly interest and rounds payment amounts to cents. We compare the scheduled payment with $50 extra principal every month, then add a $500 one-time principal payment in month six.
| Scenario | Payoff month | Total interest | Total paid |
|---|---|---|---|
| Scheduled only | 36 | $1,142.29 | $13,142.29 |
| Add $50 / month | 32 | $993.77 | $12,993.77 |
| Add $50 / month + $500 in month 6 | 30 | $926.87 | $12,926.87 |
Download this example’s CSV · Load the inputs in the calculator
The first payment reveals the model
The monthly rate is 6 ÷ 1,200 = 0.005. First-month interest is $12,000 × 0.005 = $60. The formula gives a scheduled payment of $365.06 after rounding, so $305.06 reduces principal. Without extra payments, the first closing balance is $11,694.94. With $50 extra, it becomes $11,644.94.
Compare the entire schedule
A smaller balance creates less interest in the next period. The recurring $50 overpayment therefore changes both the payoff month and total interest. The one-time $500 payment reduces the balance again in month six. Neither strategy changes the nominal interest rate or automatically lowers the scheduled payment in this model.
Inspect the last payment
The monthly formula is rounded to cents, so the last installment is adjusted to the amount actually owed. Extra principal is also capped: the tool will not collect an oversized $500 payment if less principal remains. A one-time payment scheduled after the debt is already repaid is not charged at all.
The contract matters more than the illustration
This calculator excludes prepayment penalties, fees and daily-interest conventions. Some lenders apply extra funds toward future installments unless you give instructions. Confirm allocation rules and obtain a lender payoff quote before acting. A lower modeled interest total alone does not establish that an overpayment is the best use of your cash.
Independent reproduction
The published totals were checked with a separate Python Decimal recurrence using 40-digit precision and half-up cent rounding. It did not call the JavaScript calculator. Download the verification script from our methods page to reproduce that reference. The CSV contains every installment for all three scenarios, not only the headline saving.